Important information The website is for use by Institutional Investors (as defined by the Securities and Futures Act) and/ or financial intermediaries
Please read this page before proceeding. By clicking to “OK” this site, the entrant has agreed that he/she has reviewed and agreed on the terms contained herein in their entirety including any legal or regulatory rubric and has consented to the collection, use and disclosure of his or her personal data as set out in the Privacy referred to below.
The information contained in this website is made available for informational purposes only. Any form of publication, duplication, extraction, transmission and passing on of the contents of this website is impermissible and unauthorised. Local Restrictions
This website or information contained or incorporated in this website has not been, and will not be submitted to, become approved/verified by, or registered with, any relevant government authorities under the local laws. This website is not intended for and should not be accessed by persons located or resident in any jurisdiction where (by reason of that person's nationality, domicile, residence or otherwise) the publication or availability of this website is prohibited or contrary to local law or regulation or would subject any AllianzGI entity to any registration or licensing requirements in such jurisdiction. It is your responsibility to be aware of, to obtain all relevant regulatory approvals, licenses, verifications and/or registrations under, and to observe all applicable laws and regulations of any relevant jurisdiction in connection with your entrant to this Website.
This website or information contained or incorporated in this website have been prepared for informational purposes only without regard to the investment objectives, financial situation, or means of any particular person or entity. The details are not to be construed as a recommendation or an offer or invitation to trade any securities or collective investment schemes nor should any details form the basis of, or be relied upon in connection with, any contract or commitment on the part of any person to proceed with any transaction. The details are also not to be construed as soliciting/promoting any financial products or services or a recommendation to purchase or sell any particular security or strategy or an investment advice. Forward-looking statements
The views and opinions expressed in this website or information contained or incorporated in this website, which are subject to change without notice, are those of Allianz Global Investors at the time of publication. While we believe that the information is correct at the date of this material, no warranty of representation is given to this effect and no responsibility can be accepted by us to any intermediaries or end users for any action taken on the basis of this information. Some of the information contained herein including any expression of opinion or forecast has been obtained from or is based on sources believed by us to be reliable as at the date it is made, but is not guaranteed and we do not warrant nor do we accept liability as to adequacy, accuracy, reliability or completeness of such information. The information is given on the understanding that any person who acts upon it or otherwise changes his or her position in reliance thereon does so entirely at his or her own risk without liability on our part. There is no guarantee that any investment strategies and processes discussed herein will be effective under all market conditions and investors should evaluate their ability to invest for a long-term based on their individual risk profile especially during periods of downturn in the market. The content may contain statements that are not purely historical in nature but are forward-looking statements, which are based on certain assumptions, risks and uncertainties. Actual events may differ from the those assumed. There can be no assurance that forward-looking statements will materialised or actual market conditions and/performance results will not be materially different or
worse than those presented.
No information on this website constitutes business, financial, investment, trading, tax, legal, regulatory, accounting or any other advice. If you are unsure about the meaning of any information provided, please consult your financial or other professional adviser. No Liability
Allianz Global Investors shall have no liability for any loss or damage arising in connection with this website or out of the use, inability to use or reliance on the contents by any person, including without limitation, any loss of profit or any other damage, direct or consequential, regardless of whether they arise from contractual or tort (including negligence) or whether Allianz Global Investors has foreseen such possibility, except where such exclusion or limitation contravenes the applicable law. You may leave this website when you access certain links on this website. Allianz Global Investors has not examined any of these websites and does not assume any responsibility for the contents
of such websites nor the services, products or items offered through such websites.Allianz Global Investors shall have no liability for any data transmission errors such as data loss or damage or alteration of any kind, including, but not limited to, any direct, indirect or consequential damage, arising out of the use of this website.
The global economy is bending under successive shocks, but not breaking. Following the disruption from US tariffs, the Middle East crisis now appears to be stabilising. But oil prices remain elevated, inflation is still above target in most major economies, and the macro backdrop remains vulnerable to renewed volatility ahead of the US mid-term elections.
What matters for investors is not just market direction, but the range of possible outcomes. Gaps across regions, asset classes and narratives are widening: the US remains relatively resilient, while Europe and parts of Asia are more sensitive to shifts in energy supply and prices. Markets are sending conflicting signals, with bonds pointing to a more stagflationary path while equities reflect a more optimistic growth backdrop.
This divergence is playing out within asset classes. Elevated inflation risk and higher-for-longer rates are shifting attention towards value, income and quality, while AI-led investment supports growth and valuations in parts of the market. Correlations between equities and bonds have risen, making diversification less straightforward and reinforcing the case for a broader toolkit.
In this environment, beta alone is unlikely to be sufficient. Returns will depend on careful choices – across countries, sectors and instruments – and the ability to adapt.
The durability of any relief rally depends on sustained normalisation of energy flows through the Strait of Hormuz and a credible political settlement. Our base case remains one of resilience – but markets are pricing a reduction in risk, not its removal.
Chart of the quarter
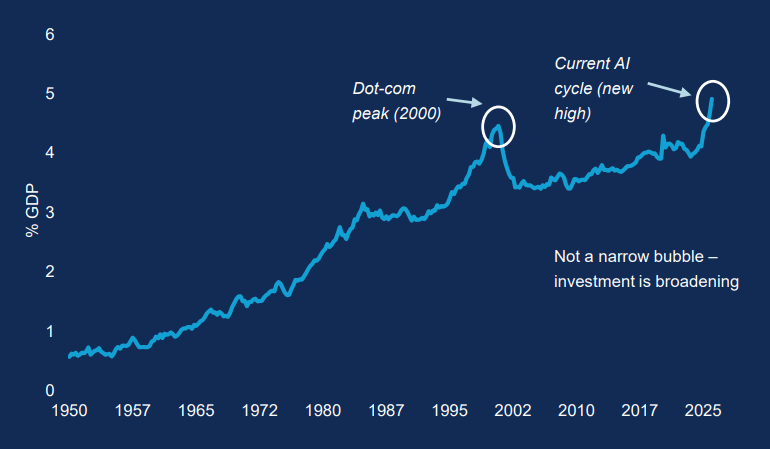
US tech investment reaches new highs
US IT investment has exceeded its dot‑com era peak as a share of GDP, underlining how the AI cycle is strengthening rather than fading. As this investment broadens beyond a narrow group of firms, identifying the winners becomes more critical for investors – and more challenging.
Source: Bloomberg and AllianzGI Economics & Strategy (data as at May 2026).
Short on time? Download the summary of our House View Q3.
Asset class convictions
Asset class convictions: equities
AI infrastructure is shifting from training (building models) to deployment at scale. This is broadening demand beyond graphics processing units (GPUs), pointing to diversified opportunities across semiconductors, data centre equipment, and enabling technologies.
Value stocks show promise, providing diversification in an AI-driven market and potentially benefiting from a different macro landscape. After a long period of “Growth” and mega-cap dominance, greater volatility and the spectre of higher-for-longer rates are driving a rotation towards fundamentals.
Strategic autonomy continues to grow in importance, and not just in Europe. This is evident from growing government spending on defence, energy and key infrastructure, supporting corporate activity across sectors. Beyond defence, the drive for autonomy is also evident in energy transition, digital and financial infrastructure, and manufacturing.
In Asia, equities are well positioned to benefit from global themes, particularly infrastructure, defence, and AI spending. China stands out given the rapid diffusion of AI across its economy. A broad ecosystem is emerging, spanning hardware, software and infrastructure, supported by strong domestic supply chains and deep STEM talent.
The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.
Asset class convictions: fixed income
In the current environment, where the distribution of possible scenarios is unusually wide, security selection increasingly outweighs beta as a driver of return.
Yields have risen significantly in core rates markets, yet credit markets have not adjusted, revealing shocks are being absorbed differently across asset classes. Looking across regions and asset types, actively managing duration and focusing on higher‑quality credit can help smooth out volatility in stocks and interest rates.
Emerging markets (EM) offer opportunities but demand a selective approach, such as favouring oil exporters over importers. We also like long 15-year Peruvian and 10-year Brazilian local rates.
Early signs of a reflationary trend in China could make the renminbi one of the best diversifiers. Consider a structural long renminbi over the US dollar.
In credit, we prefer financials and consumer non cyclicals with a tilt towards investment grade, and we are cautious on consumer cyclicals.
Despite noise around private credit, overall credit fundamentals remain solid across public credit markets with low default rates. Any spread widening could be a buying opportunity.
The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.
Asset class convictions: multi asset
Despite a fragile geopolitical backdrop, we remain positive on equities, more so from a systematic than fundamental perspective, with a preference for the US and EM over Europe and Japan.
With AI also becoming an important driver of EM performance, concentration risk should be managed within a broadly diversified portfolio.
In fixed income, we see fundamental value in bonds, even though the market cycle remains challenging. We prefer EM bonds and, within credit, favour US and European investment grade bonds over high yielders.
In FX, we have returned to a neutral view on the US dollar after its recent decline. Over the medium term, we see scope for renewed weakness as safe-haven demand eases and valuation and rate headwinds reassert themselves.
We are constructive on gold in an environment where questions about central bank independence and the US dollar may return to the fore. We continue to be long commodities as a key diversifier, with our preference for gold balanced by a more neutral stance on gas, oil, copper and silver. Given the uncertainty, we also use option strategies to enhance diversification in many portfolios.
The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management's current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.
Private markets - mid-year outlook
Resilience and return potential: Private markets are well positioned to deliver attractive risk-adjusted returns, supported by higher base rates, tighter bank regulation and wider spreads, which continue to create opportunities relative to public markets.
Focus on fundamentals: Recent headlines have heightened scrutiny around valuations, redemptions and late-cycle risks, reinforcing a focus on fundamentals, greater transparency and more conservative structures.
Diversification remains essential: Allocating across strategies, vintages, geographies and primary and secondary investments helps manage uncertainty, smooth deployment and avoid concentration risks.
Rising importance of selectivity: Greater dispersion across assets and managers increases the need for robust underwriting, strong covenants and platforms with deep origination and workout expertise.
Secondaries as a core allocation: In our view, LP- and GP-led secondaries provide access to seasoned portfolios, enhanced liquidity and potentially attractive entry points.
Infrastructure driven by secular themes: Geopolitical volatility strengthens the case for energy security and independence, while digitalisation and decarbonisation drive demand, particularly in areas such as data centres, grids and storage.
Private credit remains compelling: Its growing role in mid-market financing, alongside rising demand for infrastructure credit, direct lending across Europe and Asia, and low-correlation impact strategies, underpins continued growth.
Private equity gradually recovering: Improving exit activity may support a recovery, while liquidity constraints continue to drive demand for secondaries.
Dive deeper into our House View analysis
Our latest thinking on macroeconomics and markets, plus high-conviction ideas from our asset class CIOs.
Download our House View Q3 2026 (full version)
Our full House View includes comprehensive analysis and proprietary data on investment markets.
This document reflects the views of Allianz Global Investors’ investment leadership going into Q3 2026. Past performance does not predict future returns. The statements contained herein may include statements of future expectations and other forward-looking statements that are based on management’s current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in such statements. We assume no obligation to update any forward-looking statement.
Investing involves risk. The value of an investment and the income from it may fall as well as rise and investors might not get back the full amount invested.
Past performance does not predict future returns. If the currency in which the past performance is displayed differs from the currency of the country in which the investor resides, then the investor should be aware that due to the exchange rate fluctuations the performance shown may be higher or lower if converted into the investor’s local currency.
This is for information only and not to be construed as a solicitation or an invitation to make an offer to buy or sell any securities. The views and opinions expressed herein, which are subject to change without notice, are those of the issuer or its affiliated companies at the time of publication. The data used is derived from various sources and assumed to be accurate and reliable at the time of publication. but it has not been independently verified; its accuracy or completeness is not guaranteed and no liability is assumed for any direct or consequential losses arising from its use, unless caused by gross negligence or willful misconduct. The duplication, publication, extraction or transmission of the contents, irrespective of the form, is not permitted, except for the case of explicit permission by Allianz Global Investors.
This material has not been reviewed by any regulatory authorities.
This document is being distributed by the following Allianz Global Investors companies: In Australia, this material is presented by Allianz Global Investors Asia Pacific Limited (“AllianzGI AP”) and is intended for the use of investment consultants and other institutional/professional investors only, and is not directed to the public or individual retail investors. AllianzGI AP is not licensed to provide financial services to retail clients in Australia. AllianzGI AP is exempt from the requirement to hold an Australian Foreign Financial Service License under the Corporations Act 2001 (Cth) pursuant to ASIC Class Order (CO 03/1103) with respect to the provision of financial services to wholesale clients only. AllianzGI AP is licensed and regulated by Hong Kong Securities and Futures Commission under Hong Kong laws, which differ from Australian laws; in the European Union, by Allianz Global Investors GmbH, an investment company in Germany, authorized by the German Bundesanstalt für Finanzdienstleistungs-aufsicht (BaFin) and is authorized and regulated in South Africa by the Financial Sector Conduct Authority; in the UK, by Allianz Global Investors (UK) Ltd. company number 11516839, authorised and regulated by the Financial Conduct Authority (FCA); in Switzerland, by Allianz Global Investors (Schweiz) AG, authorised by the Swiss financial markets regulator (FINMA); in HK, by Allianz Global Investors Asia Pacific Ltd., licensed by the Hong Kong Securities and Futures Commission; in Singapore, by Allianz Global Investors Singapore Ltd., regulated by the Monetary Authority of Singapore [Company Registration No. 199907169Z]; in Japan, by Allianz Global Investors Japan Co., Ltd., registered in Japan as a Financial Instruments Business Operator [Registered No. The Director of Kanto Local Finance Bureau (Financial Instruments Business Operator), No. 424], Member of Japan Investment Advisers Association, the Investment Trust Association, Japan and Type II Financial Instruments Firms Association; In mainland China, it is for Qualified Domestic Institutional Investors scheme pursuant to applicable rules and regulations and is for information purpose only. in Taiwan, by Allianz Global Investors Taiwan Ltd., licensed by Financial Supervisory Commission in Taiwan; and in Indonesia, by PT. Allianz Global Investors Asset Management Indonesia licensed by Indonesia Financial Services Authority (OJK); and in the Abu Dhabi Global Market by Allianz Global Investors Middle East Limited, which is authorised and regulated by the ADGM Financial Services Regulatory Authority.
Admaster: 5586710
House View archives
House View Q2 2026: Holding the line
Global markets enter the second quarter navigating a more complex backdrop than many expected at the start of the year. Growth slows yet stays resilient; sticky inflation could delay rate cuts and keep policy tight. We prioritise selective duration, quality carry, AI linked equities and remain cautious on the US dollar.
House View Q1 2026: Discipline and diversification
The global economy enters 2026 bending but not breaking. We expect growth to stay on track, creating an environment that favours risk-taking. Expect a resilient yet complex year where active management will be critical.
Markets are coming to terms with a new reality that requires caution. But this evolving backdrop may open the door to opportunities for actively positioned investors.
Longer-dated US Treasuries look more attractive after years of overvaluation. We also like US high yield, floating rate notes and some securitised assets.
Secrets of success – what Jannik Sinner and Best Styles have in common
In both elite sport and systematic investing, durable success emerges from the consistent application of a robust process under conditions of uncertainty.
You are leaving this website and being re-directed to the below website outside Singapore. This does not imply any approval or endorsement of the information by Allianz Global Investors Singapore Limited contained in the redirected website nor does Allianz Global Investors Singapore Limited accept any responsibility or liability in connection with this hyperlink and the information contained herein. Please keep in mind that the redirected website may contains funds and strategies not authorized for offering to the public of Singapore. Besides, please also take note on the redirected website’s terms and conditions, privacy and security policies, or other legal information. By clicking “Continue”, you confirm you acknowledge the details mentioned above and would like to continue accessing the redirected website. Please click “Stay here” if you have any concerns.
Welcome to Allianz Global Investors
Retail Investor
Institutional Investor
External Twitter Content
This Twitter component is loaded through Twitter . Google is collecting information about your interaction with this Twitter by using cookies and may use this for targeting their offers. Please accept cookies in order to show the video.
Remember Me Cookie Dependent Disclosure
This Twitter component is loaded through Twitter . Google is collecting information about your interaction with this Twitter by using cookies and may use this for targeting their offers. Please accept cookies in order to show the video.